Two of the most talked-about new-age products in the Indian health insurance market are Niva Bupa Aspire and ICICI Lombard Elevate. We have fact-checked the viral comparisons and compiled an unbiased breakdown to help you make an informed decision.
One of my clients received these comparisons on WhatsApp. I am trying to decode this comparison on the besis of Policy Wordings
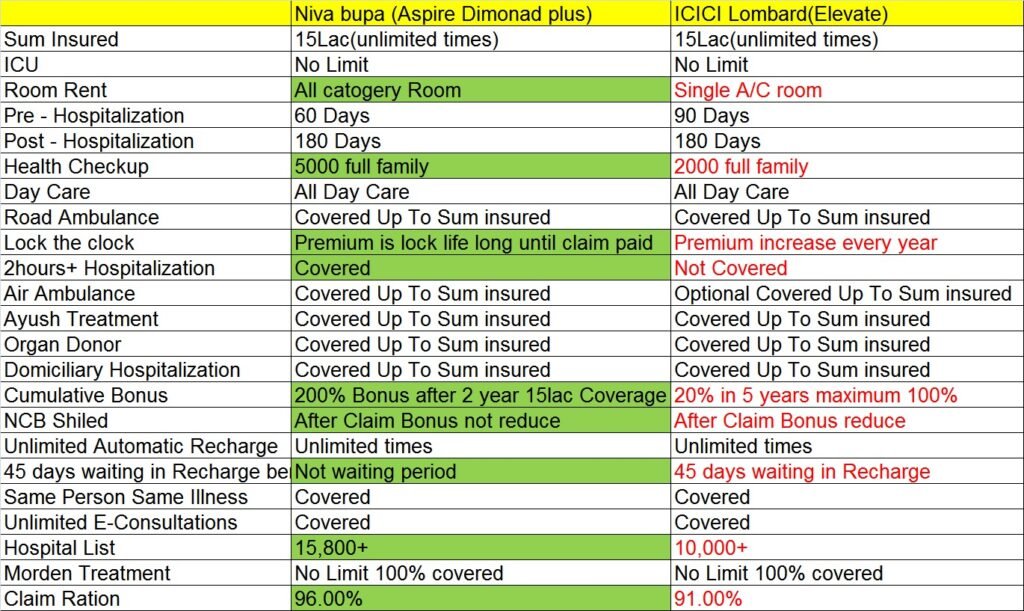
The "False Stories" vs the Real Policy Wordings
1. The Premium "Lock the Clock" Reality
- The Myth: Niva Bupa’s premium is completely locked forever until a claim is paid, whereas ICICI Lombard increases every single year.
- The Reality: Niva Bupa Aspire features an innovative “Lock the Clock” benefit that locks your premium rate based on your entry-age slab. However, this is not an absolute freeze against inflation—any regulatory portfolio repricing approved by the IRDAI will still alter your base cost. ICICI Lombard Elevate adjusts premium rates by age brackets as standard, but offers up to a 30% wellness discount to incentivize a healthy lifestyle.
2. The No-Claim Bonus (NCB) Showdown
- The Myth: Niva Bupa gives a flat 200% bonus within 2 years, while ICICI Lombard caps it at 100% and slashes it when you file a claim.
- The Reality: ICICI Lombard Elevate actually guarantees that your accumulated bonus does not reduce upon filing a claim. Through their Power Booster Add-on, the sum insured increases by 100% every single year regardless of claims history. Meanwhile, Niva Bupa Aspire’s Booster+ carries forward unutilized sum insured up to 10X (1000%), but this maximum cap applies only if you enter the policy between ages 18–35. The multiplier drops to 3X if you buy it after age 46.
3. The 45-Day Refill Rule
- The Myth: ICICI Lombard forces a 45-day waiting period before your sum insured refills, while Niva Bupa fills it immediately.
- The Reality: Both insurers provide unlimited, 100% restoration of your sum insured for subsequent hospitalizations. The 45 days mentioned in ICICI Lombard’s prospectus is a standard relapse clause. It simply means if the same individual gets hospitalized again for the exact same medical complication within 45 days, it is counted as a continuation of the initial claim rather than a separate restoration trigger.
Head-to-Head Feature Comparison
Evaluating health insurance coverage means assessing how individual policy features match your household’s requirements:
| Key Feature | Niva Bupa Aspire (Diamond+) | ICICI Lombard Elevate |
|---|---|---|
| Sum Insured Options | Offers comprehensive mid-to-high tiers | Highly customizable architecture |
| Room Rent Caps | No Capping (Any category covered) | Single Private A/C Room by default |
| Pre-Hospitalization | Covers medical expenses for 60 Days | Covers medical expenses for 90 Days |
| Post-Hospitalization | Covers medical expenses for 180 Days | Covers medical expenses for 180 Days |
| Maternity Benefit | Inbuilt up to specified limits + day 1 newborn cover | Available as an optional add-on |
Operational Performance Metrics
When comparing the best health insurance companies in India, marketing brochures only tell half the story. You must check how efficiently they pay out claims. Below is the audited performance data compiled from recent industry disclosures:
- Claim Settlement Ratio (CSR): Niva Bupa Health Insurance maintains a steady three-year average CSR of 92.92%, reaching 94.44% in FY 2025–26. ICICI Lombard Health Insurance holds a three-year average CSR of 84.50%. Niva Bupa holds a quantitative edge in settling a higher volume of filed claims.
- Incurred Claim Ratio (ICR): Both insurers display strong financial health, with Niva Bupa tracking at roughly 72% and ICICI Lombard at 71%. An ICR within the 60%–80% bandwidth indicates the company is pricing its premiums sustainably while maintaining healthy claim distributions.
- Grievance and Complaint Volume: ICICI Lombard maintains a lower customer friction rate with only 10.67 complaints per 10,000 claims processed. Niva Bupa tracks slightly higher at roughly 16 complaints per 10,000 claims, making ICICI Lombard a strong pick for overall operational dispute management.
- Cashless Network Footprint: Both brands offer extensive medical accessibility. Niva Bupa spans across 10,500+ cashless hospitals, while ICICI Lombard provides direct billing privileges across 13,000+ medical centers countrywide.
Final Verdict: Which Policy Meets Your Goals?
- Select Niva Bupa Aspire if: You are planning to secure your plan early in life (under age 35) to benefit from the entry-age premium retention structure, prefer absolute freedom regarding hospital room choices, or want a high-value unutilized rollover bonus.
- Select ICICI Lombard Elevate if: You want a customizable policy layout, need 90 days of extensive pre-hospitalization coverage, value a lower overall customer complaint ratio, or want a shield against inflation through custom add-ons.
Frequently Asked Questions (FAQs)
The Claim Settlement Ratio reflects the percentage of total claims an insurance firm successfully pays out against the total claims it receives over a financial year. A consistent CSR above 90% indicates a highly reliable claim ecosystem.
No. The feature secures the premium rate assigned to your specific age of entry. However, if the insurer initiates a portfolio repricing or if medical inflation demands a structural baseline premium adjustment across the board, your absolute premium amount can still adjust up with IRDAI authorization.
No. Unlike older, traditional health insurance policies that penalize claims by reducing your No-Claim Bonus (NCB), the base architecture of ICICI Lombard Elevate ensures that your earned accumulation does not experience a penalty reduction when a claim is processed.
An optimal ICR generally tracks between 60% and 80%. If the ratio falls below 50%, it indicates the insurer might be restricting payouts tightly or overpricing policies. If it trends above 90%, it implies potential long-term financial strain on the insurer, which could result in aggressive premium spikes during your renewals.